
I was asked a set of questions a while ago about how someone with my background ends up looking at crypto, and I have been asked versions of the same questions often enough since that it seems worth writing the answers down properly. For context: I have spent more than fifteen years in trading and analytics, at investment banks and hedge funds, managing more than $300 million in assets along the way, and over the last crypto cycle my trading returned more than 2,200 per cent. That last number is usually what prompts the questions. These are the ones that come up most, with the answers I actually give.
You spent fifteen years in energy and macro. Why look at crypto at all?
Because a liquid market is a liquid market. Trading crypto is similar to modelling any other dataset, and the larger coins are liquid enough that they behave like financial assets rather than like collectibles. Markets are cyclical. They move in phases and trends, and a phase has a beginning, an end and a duration that can be identified, and the same structures show up at every timescale, from minutes to years. Mathematicians call that a fractal pattern. Once you have learned to find those structures in oil or in rates, finding them in Bitcoin is not a different skill. It is the same skill on a noisier series.
How does an engineering degree help with any of this?
Engineering is a mathematical degree, and more importantly it is a degree in solving real problems from first principles rather than from a textbook answer. That is the whole of trading, in the end. You are using mathematical methods to model a system and to manage your risk inside it, and the ability to build the model yourself, state its assumptions and know where it breaks is worth more than any amount of received wisdom about what a chart pattern means. I wrote about the MEng at UCL and what carried over from it in a separate post.
What did you take from Oil Analytics that applied to crypto?
Two things, and neither of them is about crypto specifically.
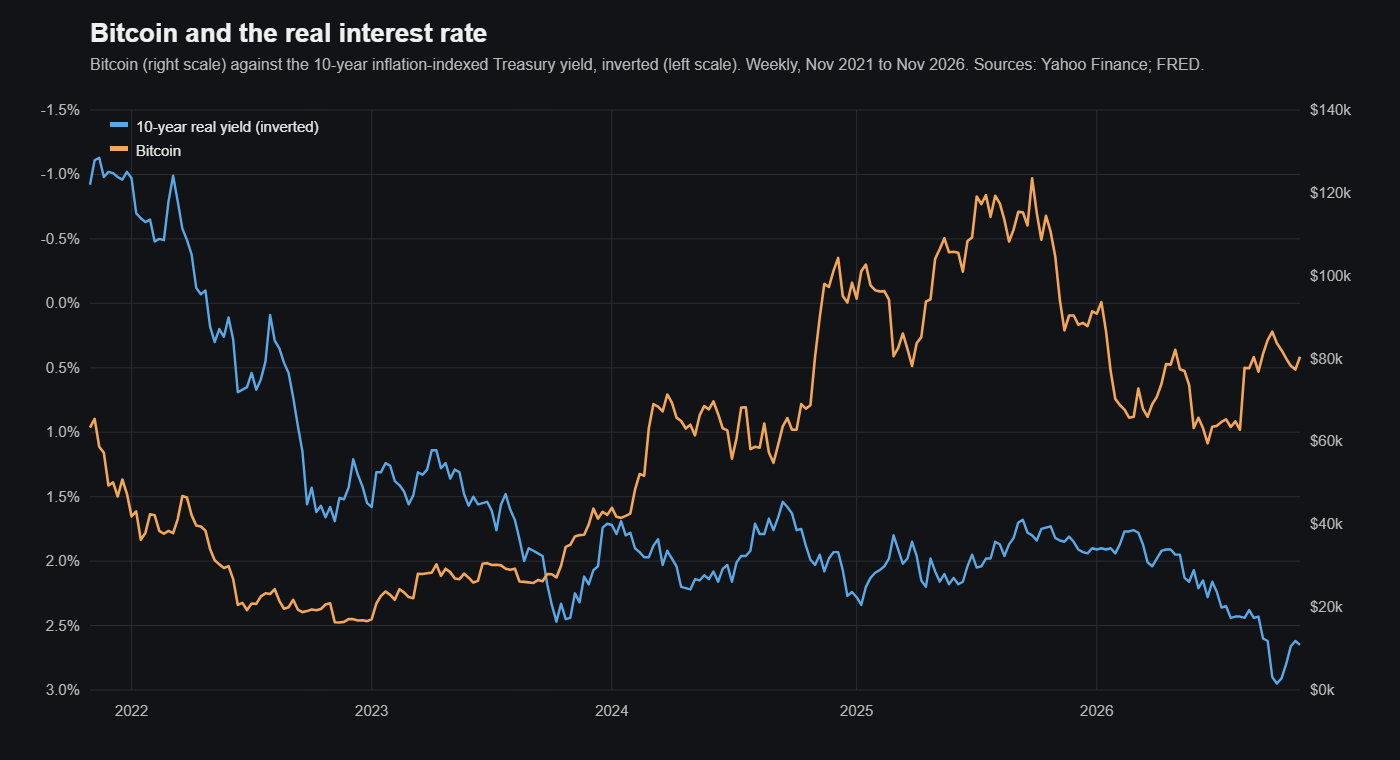
The first is the macro edge. Bitcoin’s main claim is that it is a hedge against inflation, a kind of digital gold, and whatever one thinks of that claim it means the price responds to the same things gold responds to: real interest rates, the yield curve, the money supply. There is a consistent inverse relationship between Bitcoin and inflation-adjusted bond yields, and you cannot read that relationship without a proper understanding of where the macro cycle is. That understanding is what the energy work gave me.
The second is a particular kind of model. At Oil Analytics we built refinery and petrochemical models that emulate the linear programming optimisers the plants themselves use to decide what to run. As part of modelling the asset base of the oil majors we built detailed models of ethylene crackers, and because crackers sit at the base of the plastics supply chain, their margins and utilisation turn before the manufacturing surveys do. That gave us early sight of economic turns, and an early read on the cycle is the single most valuable input to any macro view, in any asset. I have written about the cracker indicator on its own.
Combining that kind of macro insight with quantitative modelling is the only edge I trust. It works in energy and it works in anything else liquid enough to model.
What was the thinking behind your crypto trading?
It started as an inflation trade, not a crypto trade. I have been reading economic cycles for most of my adult life and I have always paid particular attention to debt and to how central banks respond to it. A decade of money creation after the financial crisis had not produced inflation, for reasons I set out in another post, but it had produced an enormous stock of liquidity. When the pandemic stimulus went directly to households on top of that, with supply chains constrained at the same time, the conditions for a sharp rise in inflation, and for a speculative surge in anything positioned as an inflation hedge, were in place.
The historical analogy I kept in mind was the Dutch tulip market in the seventeenth century, when the price of a fashionable bulb briefly matched the price of a house on an Amsterdam canal. What is interesting about tulip mania is not that it happened but that it did not matter much: the Dutch Republic was the leading economy of its age and the collapse barely touched it, because the bubble was contained to a group of speculators and never reached the real economy. The crypto surge had a similar character. Institutional money was largely absent, so there was no systemic risk, and central banks had no reason to intervene. That combination, a speculative market running on excess liquidity without any brake from policy, is rare, and it was identifiable in advance to anyone watching the macro picture.
Fundamental analysis told me the conditions existed. Quantitative analysis told me how to size and time the exposure. Neither on its own would have been enough, and the 2,200 per cent came from having both, not from either.
Do you believe in crypto?
Not in the way the people who ask usually mean. It is not my primary market and I am not persuaded by the long-term case for most of what trades in it. But I think you can hold that view and still take the market seriously as a market, with the same discipline about risk you would apply to anything else. A trader’s job is to understand what is in front of them, not to approve of it.