
I have an argument I keep getting into, so I am going to write it down. The argument is that the pandemic, for all the harm it did, is the only reason the developed world is not still stuck in the low-inflation, low-growth trap it had been in for a decade. Nothing central banks did in those years worked. The pandemic worked, by accident, and the reason it worked tells you something about how money actually reaches an economy.
The decade before
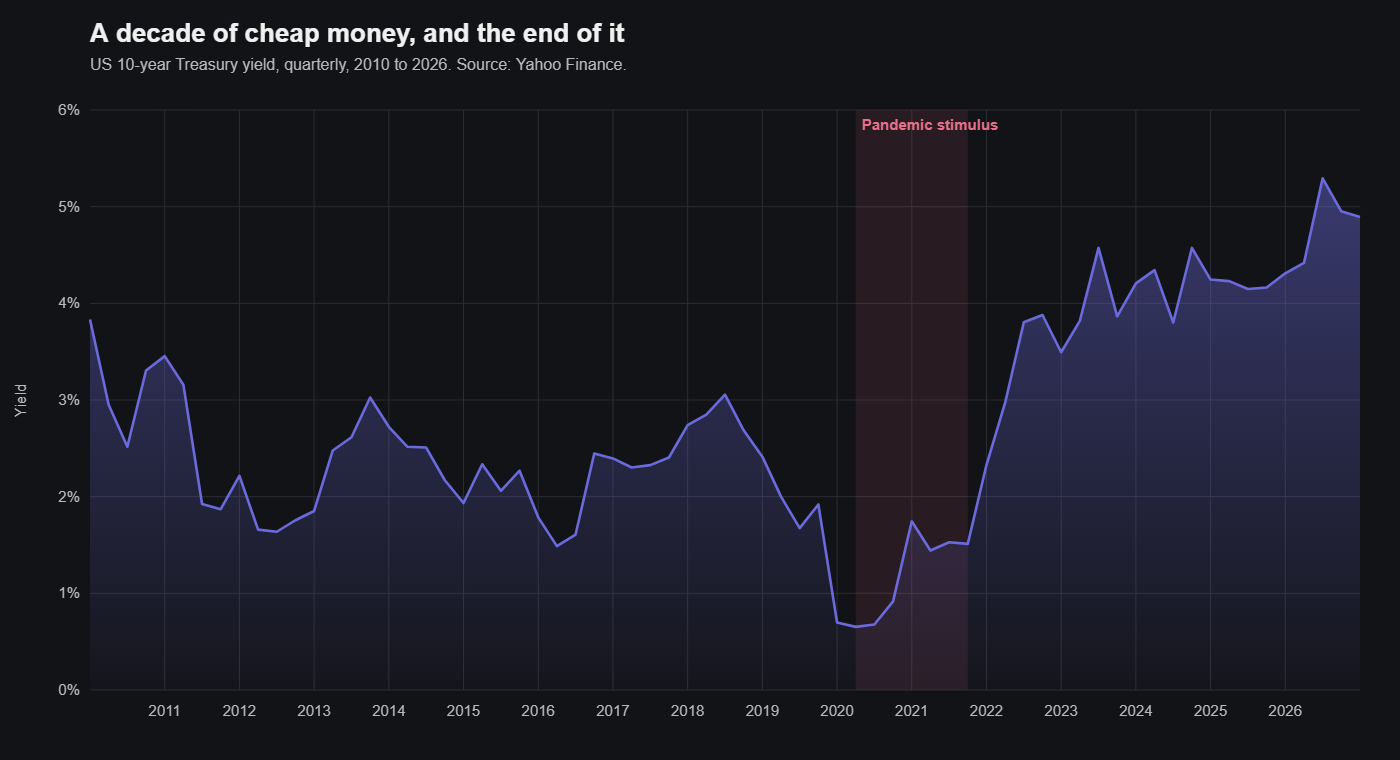
For most of the ten years before the pandemic, inflation in the United States, the euro area, the UK and Japan ran below the 2 per cent that their central banks were aiming for, and in Japan and parts of Europe it ran close to zero or below it. This was not for lack of effort. Interest rates were cut to zero and, in Europe and Japan, below zero. Central banks bought trillions of dollars, euros and yen of government bonds through quantitative easing. The money supply, on the central banks’ own balance sheets, expanded enormously. And inflation stayed where it was.
The usual explanation was structural. Ageing populations save rather than spend. Technology makes goods cheaper every year. Globalisation had moved manufacturing to wherever labour was cheapest, which held wages down in rich countries and prices down everywhere. Those forces are real and they were pushing the right way for low inflation. But I think the more important reason the policy did not work is simpler than that. The money never arrived.
Quantitative easing works by buying bonds from banks and investors. It pushes up asset prices, it lowers long-term interest rates, and it leaves the banking system with a great deal of reserves. What it does not do is put money in the hands of someone who is going to spend it on a car or a kitchen. The liquidity sat in the financial system, inflated the price of the things the financial system owns, and barely touched the price of bread. Anyone who traded through that period remembers how strange it was to watch equity indices make new highs year after year while the inflation prints came in soft every month.
What the pandemic changed
When the lockdowns came, governments did something they had refused to do for a decade: they sent money directly to people. Furlough schemes paid wages. Cheques went to households. Grants and guaranteed loans went to businesses. The scale was unprecedented, but the scale was not the point. The point was the channel. For the first time since the financial crisis, the stimulus went into the real economy rather than the financial one, and it went in at exactly the moment when there was almost nothing to spend it on.
So households saved it, involuntarily, and when the restrictions lifted they spent it all at once. Demand came back in a surge. At the same time, supply could not keep up. Factories had been shut, shipping was in chaos, and some workers never came back to the jobs they had left. Shortages pushed prices up from the supply side at the same moment that pent-up spending was pulling them up from the demand side. Labour markets tightened, workers found they could ask for more, and wages started to rise for the first time in years. Every one of the forces that had kept inflation down reversed within about eighteen months.
Why I think it is structural
The easy view is that this was a one-off and that the old regime will reassert itself once the shock has passed. I do not think so, for three reasons.
The first is that globalisation has gone into reverse. Companies that discovered during the pandemic that their entire supply of some component came from one factory on the other side of the world have been bringing production closer to home and holding more inventory. That is sensible, and it is more expensive, and the cost shows up in prices.
The second is that labour has more bargaining power than it had. Some of the people who left the workforce have not returned, the demographic trend is doing the rest, and a worker who can ask for more will. Wage growth feeds into prices and prices feed into wage demands, and that loop, once it is running, does not stop on its own.
The third is political. Before the pandemic, large-scale fiscal stimulus was something governments would not do, and the whole burden of supporting the economy fell on central banks that could only act through the financial system. The pandemic showed that governments can, when they choose, put money directly into people’s accounts, and that it works. That knowledge does not go away. The next downturn will be met with fiscal policy as well as monetary policy, and fiscal policy is inflationary in a way that quantitative easing never was.
The counterfactual
Suppose there had been no pandemic. Interest rates were already at zero, so there was no room to cut. The structural forces, demographics, technology and globalisation, were all still pushing in the same direction. And there was no political appetite anywhere for the kind of fiscal programme that eventually broke the spell. I find it hard to construct a story in which inflation returns to target on its own in that world. Japan is the test case: it had the longest experience of the deflationary trap, its fiscal response to the pandemic was smaller relative to the shock, and it has struggled hardest to leave the old regime behind.
None of this is to say inflation is good. It is a tax on anyone with savings and a problem for anyone whose wages do not keep pace. The point is narrower. For a decade the richest economies in the world could not generate inflation when they wanted to, and the reason was that the money they created never reached the people who would have spent it. It took a pandemic to change the channel. The central banks that spent the following years raising rates faster than at any point in a generation were cleaning up after a policy that had, at last, worked.