
The earlier posts in this series were about measuring volatility with standard deviation, which is the statistically proper way to do it. This one is about the tool I actually have on the screen most of the time, which is the average true range. It is cruder than a standard deviation, it is easier to read, and it answers the question a trader asks first: how far does this thing move in a day?
What it is
The average true range, usually just ATR, was introduced by J. Welles Wilder in his 1978 book New Concepts in Technical Trading Systems, the same book that gave us the RSI. It is simply the average, over some number of recent periods, of how far the price travelled in each period. The default is 14 periods, which on a daily chart means the last 14 days. Unlike almost every other indicator it says nothing about direction. A market falling 3 per cent a day and a market rising 3 per cent a day have the same ATR.
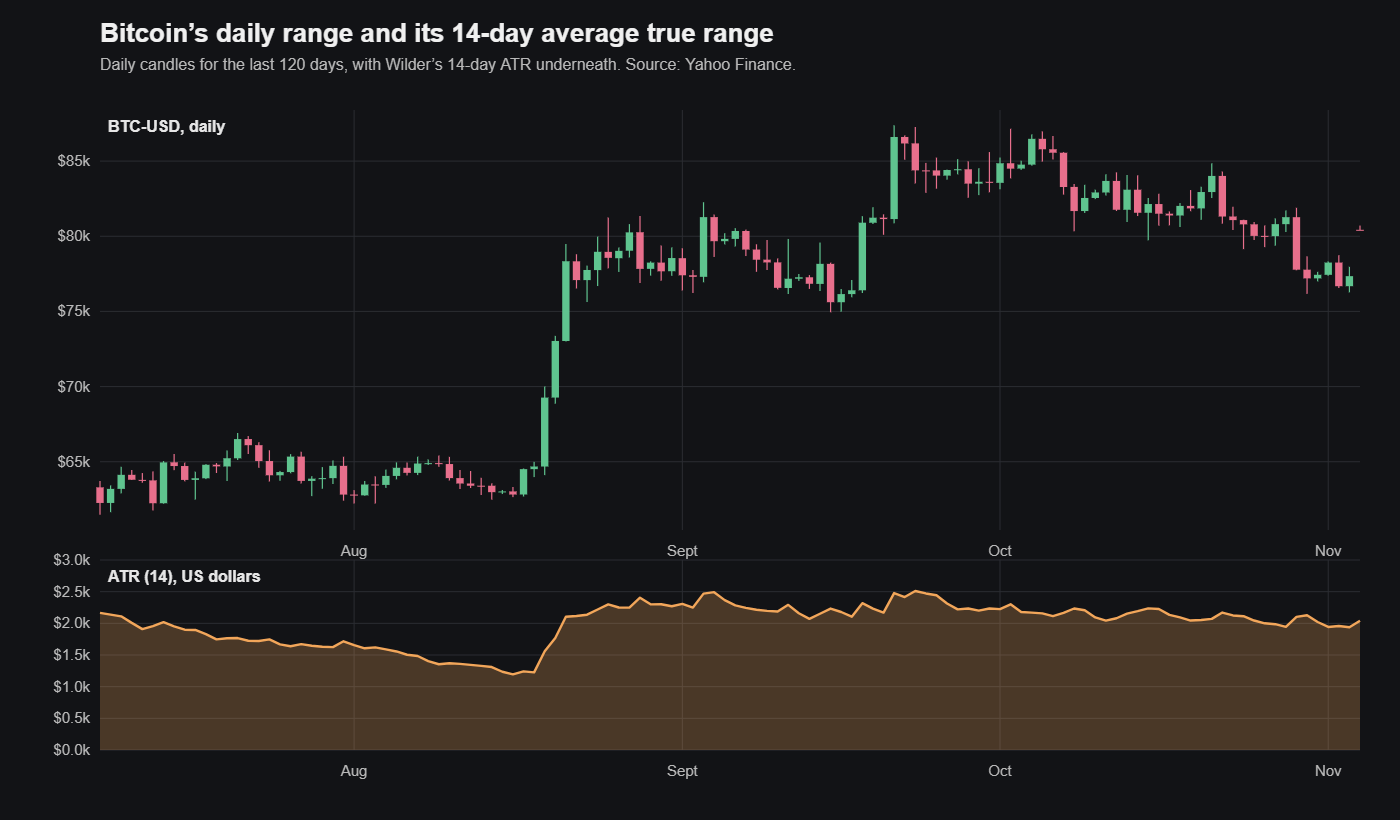
The reason I called this post the first derivative of volatility is that ATR is most useful when you watch how it changes. A standard deviation over a 100-day window tells you what volatility has been on average. A 14-day ATR responds within days, so a rising ATR tells you that volatility is increasing now, and a falling one that the market is going quiet. That rate of change is often the earliest warning you get that the regime is shifting, and it is what I look at it for.
How it is calculated
There are two steps. The first is to work out the true range for each period, which is the largest of three numbers:
- today’s high minus today’s low;
- the absolute difference between today’s high and yesterday’s close;
- the absolute difference between today’s low and yesterday’s close.
The second and third of those exist to catch gaps. If a stock closed at 102 and opened the next morning at 108, the high-minus-low of that day might be small, but the price still travelled six points overnight, and the true range picks that up where a plain daily range would miss it.
A quick example. Suppose a stock has a high of £105, a low of £100, and closed yesterday at £102. The three candidates are 105 minus 100, which is £5; 105 minus 102, which is £3; and 100 minus 102, which is £2 in absolute terms. The true range for the day is the largest of them, £5.
The second step is to average the true ranges. For the very first value you take a simple average of the first 14 true ranges. After that, Wilder used a smoothing that leans on the previous value:
\[\text{ATR}_{\text{today}} = \frac{\text{ATR}_{\text{yesterday}} \times (n – 1) + \text{TR}_{\text{today}}}{n}\]where n is the period, 14 by default. The effect is that each new day’s true range gets a weight of one fourteenth and the history gets the rest, so the ATR moves smoothly rather than jumping every time an old day drops out of the window. Every charting platform calculates it for you; the point of knowing the formula is to understand why it lags a little and why a single wild day does not swing it very far.
Reading it
A rising ATR means the daily ranges are expanding. That usually accompanies the start of a trend, a breakout from a range, or the arrival of news, and it is a signal to expect larger moves than you have been used to. A falling ATR means the ranges are contracting, which is what consolidation looks like, and long periods of falling ATR often precede a breakout, because a market that has gone quiet is usually storing up a move rather than finished with moving.
I would not trade off the direction of the ATR on its own. What it does is set expectations for the other decisions, and that is where it earns its place.
What I use it for
Stops. This is the main one. A stop that sits inside the range of a normal day will get hit by noise, and a stop far outside it exposes you to more than you intended. Placing the stop a fixed multiple of the ATR away from the entry, somewhere between one and a half and two times is common, puts it outside ordinary movement and scales it automatically when volatility changes.
Position size. If I am willing to lose a fixed amount on a trade, and my stop is two ATRs away, then the number of units I can hold is that amount divided by two ATRs. When the ATR doubles the position halves, and the money at risk on a normal bad day stays the same. This is the practical version of the volatility-based sizing I mentioned in the first post, and it is simple enough to do in your head.
Judging a breakout. If price pushes through a level that has held for weeks and the ATR is rising with it, the move has range behind it. If the ATR is flat or falling, the breakout is happening on small daily ranges and is more likely to fail. It is not a rule, but it has saved me from chasing a fair number of moves that went nowhere.
Targets. If an asset typically moves one ATR in a day, a target three ATRs away is a multi-day expectation and should be treated as one. It stops me from setting targets that the market could not plausibly reach in the time I have given the trade.
The thing to remember is that ATR is a measure of movement, not a view on where the price is going. Used as a view it is useless. Used as a ruler, to size the stop, size the position and calibrate what a normal day looks like, it is one of the few indicators I would keep if I could only keep a handful.