
Bitcoin has made new highs since the US election, and the simple explanation is the one everyone is giving: the incoming administration has promised to be friendly to crypto, and the market is pricing that in. I think the simple explanation is right as far as it goes, but it is not the part I would be watching. The part I would be watching is the Federal Reserve, and specifically what happens between the new president and the Fed chair, because that is where the real support for Bitcoin over the next few years is likely to come from, whether anyone intends it or not.
What happened last time
The first Trump administration was not pro-crypto in any stated sense. It did not need to be. What it delivered was large fiscal deficits, pressure on the Fed to keep rates low, and a generally hands-off regulatory environment, and that combination was close to ideal for an asset whose main selling point is that it exists outside the monetary system. Bitcoin’s rise in those years owed more to the macro backdrop than to anything anyone in Washington said about it.
This time the stated position is different. The campaign promised explicit support for the industry, there has been talk of the United States holding Bitcoin as a reserve asset, and the market has responded accordingly. I would treat the specific promises with some caution, because promises made to an industry during a campaign have a way of shrinking once the lawyers get involved. The macro backdrop is the more reliable thing.
The Fed is the story
Jerome Powell was nominated by Trump in 2017 and criticised by him, publicly and repeatedly, for most of the following three years over the level of interest rates. Powell’s current term as chair runs to 2026. It is a fair bet that the pressure resumes, and that when the term ends the replacement will be someone more sympathetic to lower rates. That sets up three things that are each, separately, supportive for Bitcoin.
The first is trust. A public fight between the White House and the central bank over monetary policy erodes confidence in the institution, and Bitcoin is, at bottom, a bet against institutions. Every time a central bank looks like it is being leaned on, the case for an asset that no one can lean on gets a little stronger. The commentary from prominent figures in the tech world about the Fed in recent weeks is the same sentiment from a different direction, and the audience for that commentary overlaps heavily with the audience that buys crypto.
The second is inflation. An administration that wants lower rates and larger deficits at the same time is asking for inflation, and inflation is the original argument for holding Bitcoin. It was the argument that first got me interested in it, well before the current cycle, and it is the argument that institutional allocators use when they add it to a portfolio. If inflation expectations rise again, that constituency grows.
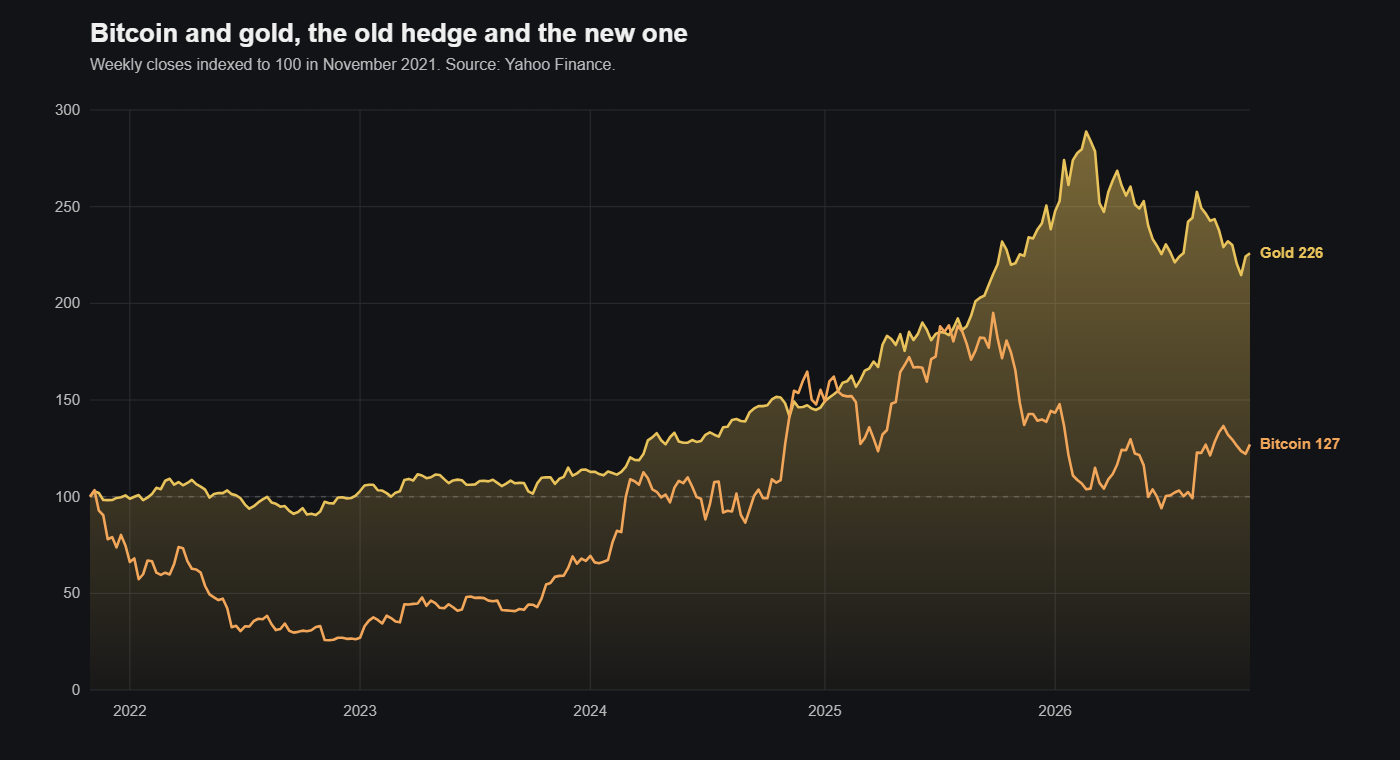
The third is volatility. Political conflict over monetary policy produces uncertainty, and uncertainty produces demand for things that behave like havens. Whether Bitcoin is a haven is a long argument, but on my numbers the 90-day correlation between Bitcoin and gold has been running around 0.76 at the time of writing, which is high, and which suggests that at least for now the market is treating the two in a similar way. That correlation will not hold in every scenario, and in a sharp risk-off move Bitcoin has historically fallen with equities rather than rising with gold. But in a slow erosion of confidence rather than a crash, the gold-like behaviour is the one I would expect to see.
The caveats
None of this is a forecast of the price. It is an argument about the direction of the forces. A friendlier regulator helps at the margin. A president fighting his central bank, a looser fiscal stance and a return of inflation worries help a great deal more, and they are more likely than not. Against that, Bitcoin is extremely volatile, has rallied a long way already, and will sell off hard on any sign that rates stay higher for longer. The thing to watch is not the next regulatory announcement. It is the next time the president mentions the Fed.