
In 2018 I became involved in the UK operation of TF Pay, which at the time was a remittance business of the traditional kind, and over the following period helped it move towards a technology-led payments model. It was a different world from trading, and most of what I learned there was about how little the technology mattered compared with everything around it. This post is about that.
What a payments business is for
Strip away the apps and the branding and a remittance business does one thing: it takes money from someone in one country and gets it to someone in another, reliably, at a cost both of them can see. A person sending part of their wages home to family. A small business paying a supplier abroad. A freelancer being paid by clients in three currencies. None of them wants a banking experience. They want the money to arrive, on the day they were told, for the fee they were quoted.
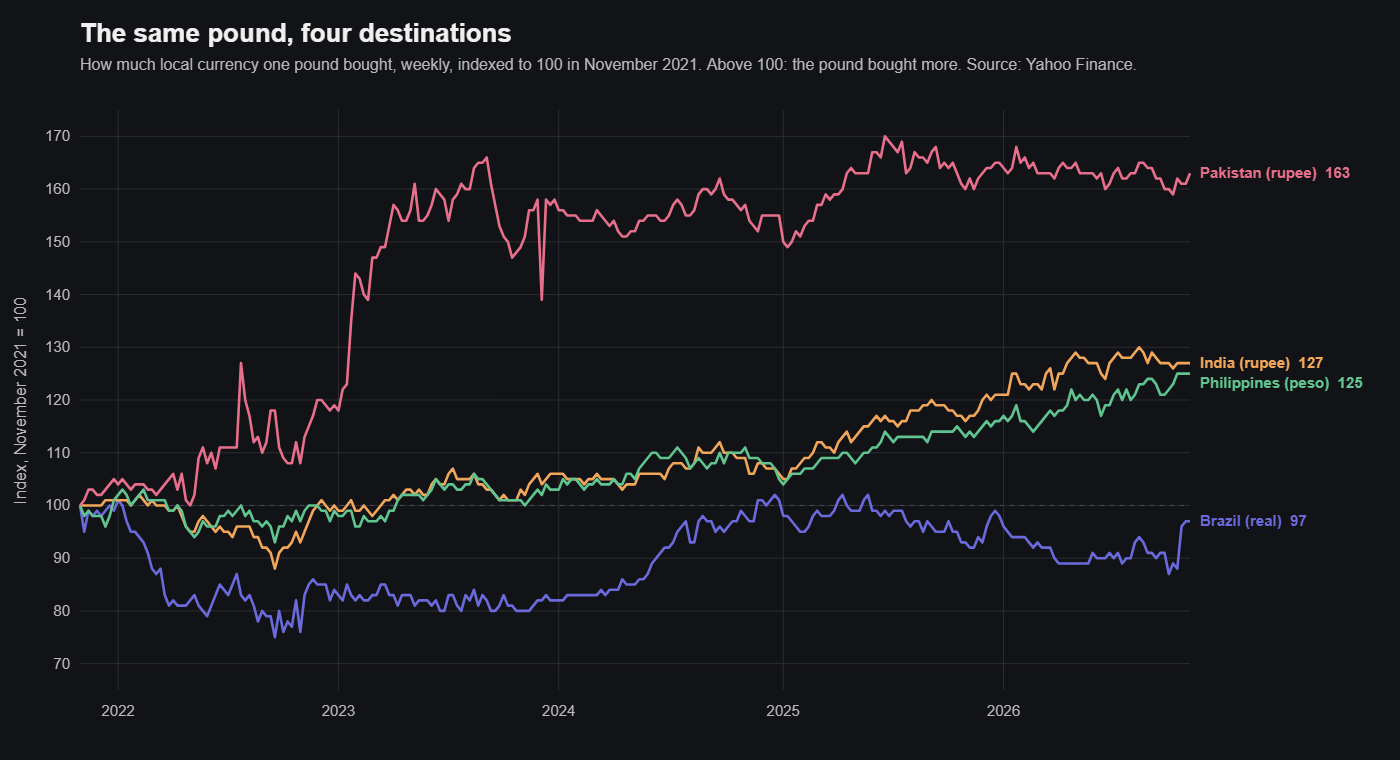
The exchange rate is the part of the transfer the customer sees and the business does not control, and it behaves very differently depending on where the money is going. The chart above follows the same pound to four countries that between them account for a large share of what is sent home from London. Over five years a pound came to buy about 60 per cent more Pakistani rupees, about a quarter more Indian rupees and Philippine pesos, and slightly fewer Brazilian reais than it did at the start, with swings of 20 per cent or more inside a single year along the way. A payments business cannot change any of that. What it can do is show the rate before the customer commits, and not add a margin on top that the customer cannot see.
The old model did that through branches, paper forms and a chain of correspondent banks, each of which took a cut and added a day. The digital model does it through a platform the customer uses on their phone, and the promise is that the same transfer becomes faster, cheaper and visible from end to end. That promise is easy to make and hard to keep, because the complexity does not disappear when the interface gets simpler. It moves behind the screen, where the customer cannot see it and the company still has to manage it.
What is actually behind the screen
A transfer that looks like one tap is, underneath, a set of banking relationships in each corridor, a liquidity position in each currency so that the money can be paid out before it has fully arrived, a foreign exchange desk or an arrangement with one, identity verification at onboarding, monitoring of transactions as the rules require, security around the personal and financial data the platform holds, and a technology stack that ties all of that together without falling over on a Friday afternoon when half the month’s volume goes through. A payments company that gets any one of those wrong has a problem the customer will notice within hours.
The commercial questions were the ones I spent most of my time on. Which corridors to prioritise, since you cannot be good everywhere at once. How to control the cost of each transaction, which is where the margin lives or dies. How to scale without the service quality dropping, because a platform that works for a thousand customers does not automatically work for a hundred thousand. And how to keep the product, the controls and the growth moving at the same pace, because a company that builds features faster than it builds the systems to support them is storing up trouble, and one that builds controls faster than it builds the product has no customers to protect.
Being boring on purpose
The lesson I took from payments is almost the reverse of the one trading teaches. In trading, an edge is something nobody else has. In payments, the edge is being dependable in exactly the ways everyone else promises to be and often is not. Fees stated upfront and not changed. Exchange rates shown before the customer commits. A transaction status that is true. Support that answers. Verification that is explained rather than sprung on people. None of that is innovative, and all of it is what builds a customer base, because trust in a financial service is slow to earn and quick to lose, and an unexpected fee or a transfer that vanishes for three days loses it.
The way I put it to the team at the time was that we were trying to be boring on purpose. The technology existed to make the boring parts reliable at scale, not to make the service exciting. The customers who stay are the ones who stopped thinking about the platform because it simply worked.
What changes next
Automation and machine learning will take on more of the work behind the screen: verification, monitoring, exchange rate management, support, risk assessment. All of it benefits from systems that can handle volume and spot patterns. What does not change is that someone has to be responsible for those systems operating fairly, accurately and securely, and that the customer’s test of the service stays exactly what it was before any of this existed. Did the money arrive, when you said it would, for what you said it would cost. Everything else is implementation.