
If you have searched for Caio Marchesani and ended up here, this is the short version of what I do. I trained as an engineer, I spent most of my working life in markets, and these days a good share of my week goes on an açaí business. People hear that list and assume it describes three unrelated careers. From the inside it has never felt like that. It is one habit applied to different problems: take something messy, find the numbers in it, make a decision, and be able to show your working afterwards.
Engineering first
I did the five-year MEng in mechanical engineering at UCL. The part I enjoyed most, and was better at than the rest, was the applied mathematics: partial differential equations, fluid dynamics, and the general business of modelling systems that will not sit still long enough to be measured properly.
I did not know it at the time, but that is also a fair description of a commodity market. When I moved into trading the maths came with me and never really left. Black-Scholes is a partial differential equation. A price chart, if you squint, is Brownian motion with a drift. The engineer’s reflex is to write the model down before you allow yourself an opinion, and I still cannot form a view on anything without doing that first.
Markets
I have worked in investment banking, in trading and in market analytics, and underneath the different job titles the work is the same. A great deal of information arrives every day, most of it is noise, and the job is to decide which small part of it matters and what to do about it before the next day’s lot arrives.
Two places shaped how I actually work. The first was Oil Analytics, where I was a partner. We built a quantitative framework for the energy market, meaning models of refineries, petrochemical plants and the supply chain that runs between them, and used it for derivatives trading, equity analysis, project evaluation and advisory work. At some point the framework was taken on as a Bloomberg data provider, and that was the moment it stopped being our internal tool and had to survive other people looking at it closely, which is a different standard and a good one to be held to.
The second was Optima Cap, a London quantitative macro energy fund, which drew on what I had learned at Deutsche Bank and at Oil Analytics. The approach there was systematic by design: mathematical models, algorithmic strategies, and risk limits decided in advance, when you are calm, rather than in the moment, when you are not. I would rather have a rule I can test than a feeling I cannot.
Why I keep writing about volatility and correlation
Most of what is on this site is the plumbing of trading: how to measure historical volatility, how to back implied volatility out of an option price, why the correlation between two assets is a moving target rather than a fact you can look up. I write about these because they are the questions people actually ask me, and because the honest answer is nearly always a method rather than a prediction. Nobody can tell you where a market will be in March. Anybody can learn to work out what the options market thinks the range will be, and that is a more useful thing to know.
Payments
In 2018 I became involved in the UK operations of TF Pay, which was a remittance business at the time and has since been rebuilt as a technology-led payments platform. The lesson there was almost the opposite of the trading one. In payments the technology is the easy part. The hard part is being boring in exactly the right ways, which means being reliable, being transparent about fees, and being easy to understand. Someone sending money to their family abroad does not want an innovative experience. They want the money to arrive on the day you said it would.
And then açaí
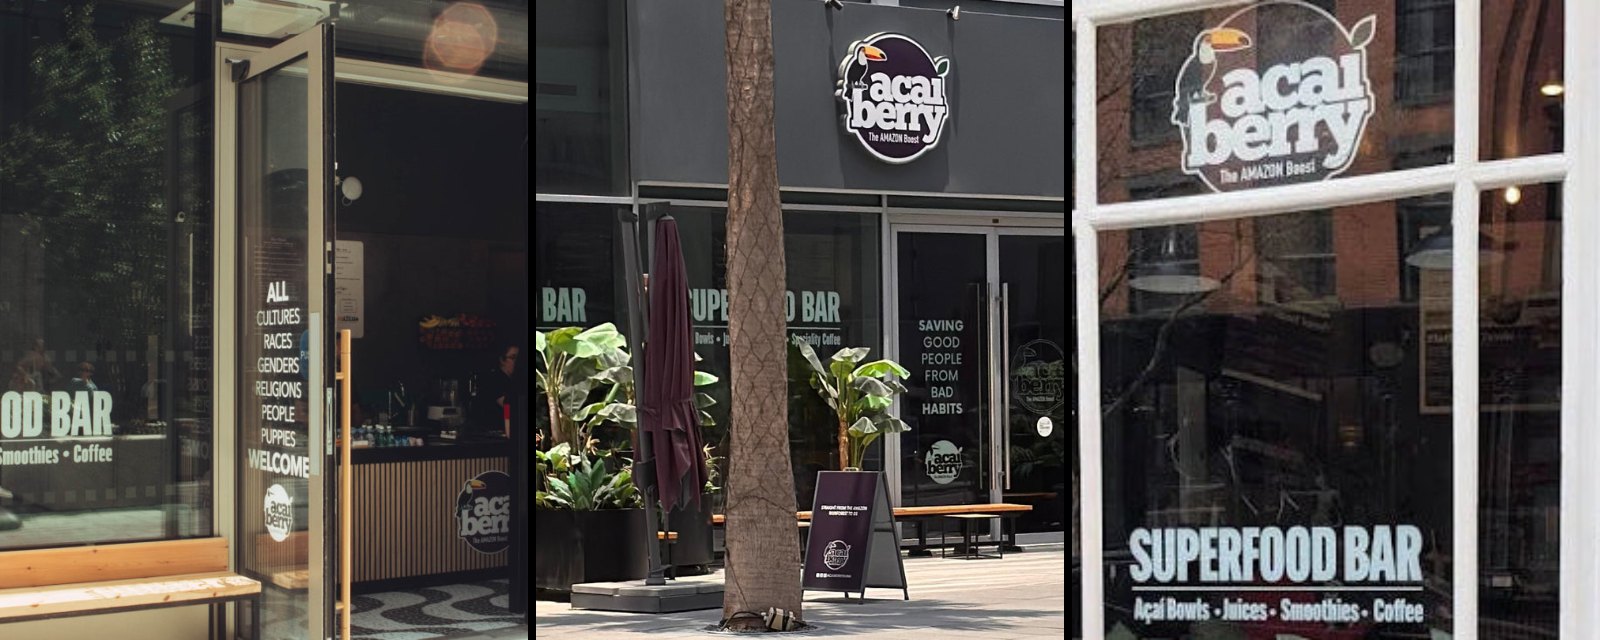
Acai Berry Foods is a chain of açaí cafés that started in London, mostly açaí bowls and the products that go with them, with shops in London, the United Arab Emirates and New York, and an online shop. I founded the business and invested in it, and my part of it is the unglamorous side: budgets, expenditure, feasibility work on new sites, and the question of whether a second shop is a good idea or just a flattering one. I have written about that side of it on its own, and separately about the London launch and the move to Dubai.
It is the same discipline as a trading desk with a much slower clock. A shop tells you whether it is working over months rather than milliseconds, the ingredients go off, and the rent does not.
What connects it
I do not have a grand philosophy about any of this. I have three things I try to do every time. I write the model down. I decide how much risk I am willing to take before I take it. And I measure the result honestly, especially when it is bad, because that is when the temptation to look away is strongest. That works for an options book and it works for a café, and it is the only method I have found that still holds up when I am tired, which is when most bad decisions get made.