Brownian motion: from pollen in water to the price of Bitcoin
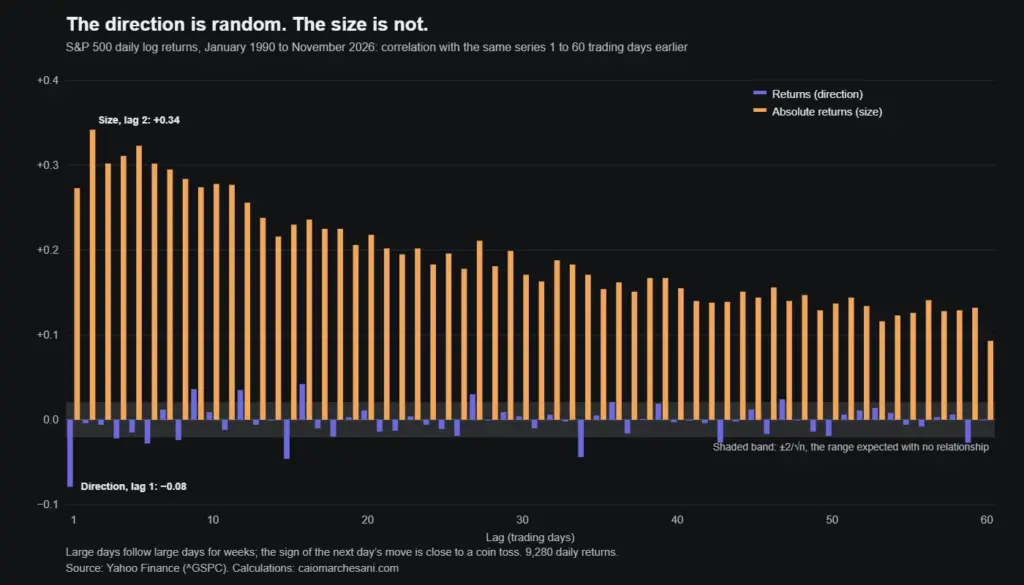
Why the same equations describe pollen in water and asset prices, and what 37 years of the S&P 500 and 12 of Bitcoin say about the random walk.
Robert Brown, a botanist, saw pollen grains jittering in water in 1827. The random motion he described became, much later, the standard assumption about how share prices move in the Black-Scholes model.
My degree was in mechanical engineering, and equations from it keep turning up in finance. From rocket science to markets is the short account of how I went from one to the other. A Falcon 9 launch and fluid dynamics stays mostly with the engineering. Brownian motion makes the crossing, checking the random-walk idea against close to 37 years of S&P 500 prices and 12 of Bitcoin’s.
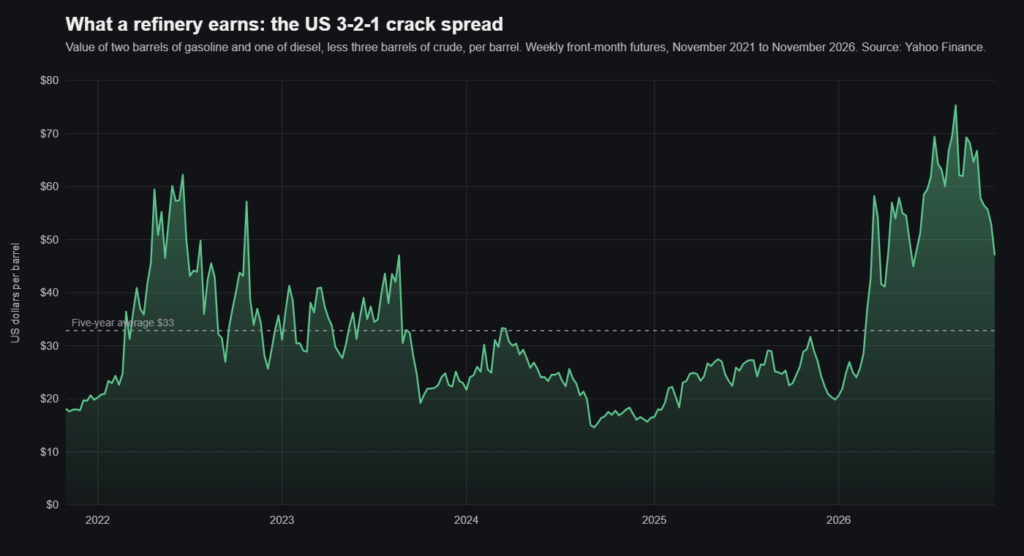
Other subjects: Macro and markets · Energy and refining · Açaí from the Amazon to the bowl
Why the same equations describe pollen in water and asset prices, and what 37 years of the S&P 500 and 12 of Bitcoin say about the random walk.
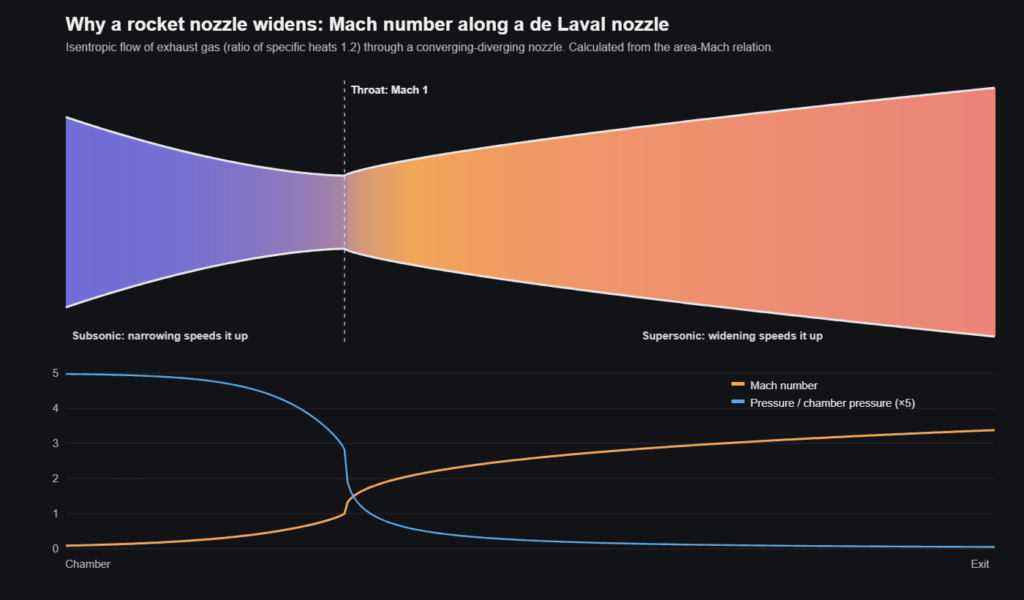
The physics behind a Falcon 9 launch, from Newton’s third law and specific impulse to why a rocket nozzle widens to make the exhaust faster.
Caio Marchesani on the move from a propulsion engineering degree at UCL to quantitative macro trading, and why modelling a system transferred unchanged.